
By Paul Onehi
Can a country build a prosperous economy by trusting its people to repay what they
borrow? That question took centre stage at the 2026 National Credit Managers Conference in Lagos, where credit professionals called for a shift from Nigeria’s cash-dominated economic culture towards a credit-driven system built on trust, financial discipline and responsible borrowing.
Organised by the National Institute of Credit Administration (NICA), the conference was held at the Civic Centre, Victoria Island, Lagos, under the theme, “The Five Pillars of a Credit-Worthy Nation.”
The event also featured the graduation of credit management professionals, the induction of new members and the presentation of the Nigeria Credit Industry Awards.
In her opening address, NICA President, Dr. (Mrs.) Markie Idowu, FICA, said an effective credit system could make homeownership, education, agriculture and industrial development more accessible to ordinary Nigerians.
She, however, stressed that the success of such a system depended not merely on financial institutions and the availability of funds, but also on the character and conduct of citizens.
“Distinguished ladies and gentlemen, let us remember this fundamental truth: a nation’s creditworthiness is built not simply on the money it possesses, but on the character, conduct and reliability of its citizens,” she said.
Idowu identified five categories of citizens necessary for building a creditworthy nation: credit-ready, creditworthy, credit-minded, credit rules-abiding and credit-sustainable citizens.
She maintained that responsible borrowing and repayment practices were essential to developing a sustainable credit culture.
Emphasising the importance of collective responsibility, she called on stakeholders to build a nation where access to credit creates opportunities and responsible Nigerians are given the opportunity to thrive. She subsequently declared the conference open.
The Founding Registrar and Chief Executive Officer of NICA, Prof. Chris Onalo, challenged Nigeria to rethink its approach to economic development, arguing that the country’s long-standing focus on infrastructure, exchange rates and other economic challenges had overlooked a fundamental question: whether Nigeria had developed a credible and sustainable credit culture.
“No nation becomes great by cash,” Onalo declared, stressing that economic prosperity depends not merely on the availability of money but also on trust, financial discipline and a functional credit system.
Citing the United States, Germany, the United Kingdom, Singapore and China, he argued that credit and trust had played significant roles in building strong economies.
He urged Nigeria to embrace a credit-driven economic model capable of expanding business opportunities, stimulating investment and supporting sustainable national growth.
According to him, Nigeria’s lending culture places excessive emphasis on collateral at the expense of borrowers’ character and credit history, while the preference for cash transactions continues to limit access to productive financing.
He further argued that the situation had left more than 39 million small businesses struggling to access loans, with trillions of naira tied up in unpaid credit facilities, thereby limiting the economy’s ability to move beyond short-term transactions towards a sustainable credit culture.
Onalo maintained that addressing these challenges required deliberate attention to five critical pillars, expressing confidence that getting them right could transform the country within a generation.
“If we get these five pillars right, Nigeria will change in one generation,” he said.
The first pillar, he explained, is integrity. He argued that no legislation could independently transform a dishonest borrower into a responsible one, insisting that repayment should be driven by personal character and a sense of obligation rather than the fear of legal consequences. “Your word is your bond,” he said.
The second is knowledge. Onalo criticised the practice of assigning credit management responsibilities to individuals without the necessary professional training, arguing that the management of credit facilities requires specialised knowledge and competence.
“Credit management is a profession, not a posting,” he said, maintaining that those entrusted with managing credit should possess appropriate professional qualifications.
The third pillar is structure. He identified delays in the administration of justice as a major concern for investors and lenders, arguing that a creditworthy nation must have an efficient judicial system capable of resolving credit disputes and enforcing loan agreements promptly.
The fourth is systems. He called for a reliable national credit database that captures borrowers’ credit histories and enables financial institutions to assess their repayment records.
According to him, technology and credible data systems are essential to improving transparency and accountability in credit administration.
The fifth pillar is leadership. He argued that political and business leaders must understand the importance of credit in economic development and create an environment that encourages responsible lending and productive borrowing.
“Credit is the oxygen that converts productivity to prosperity,” he said.
Providing further insight into the conference theme, Prof. Owolabi Sunday Ajao, FICA, Vice-Chancellor of Atiba University and Chairman of NICA’s Accreditation Committee, examined the institutional and behavioural changes required to strengthen Nigeria’s credit system during a special panel session.
Ajao argued that Nigeria’s lending culture relies excessively on collateral while paying insufficient attention to borrowers’ character, repayment capacity and credit history.
He stressed that building a sustainable credit economy required coordinated efforts among citizens, financial institutions, regulators, businesses and government.
His position reinforced the conference’s broader argument that improving access to credit goes beyond increasing the availability of funds; it also requires stronger institutions, professional standards and responsible financial behaviour.
Beyond the policy discussions, the Nigeria Credit Industry Awards recognised individuals whose professional contributions have shaped different aspects of the country’s credit and financial services industry.
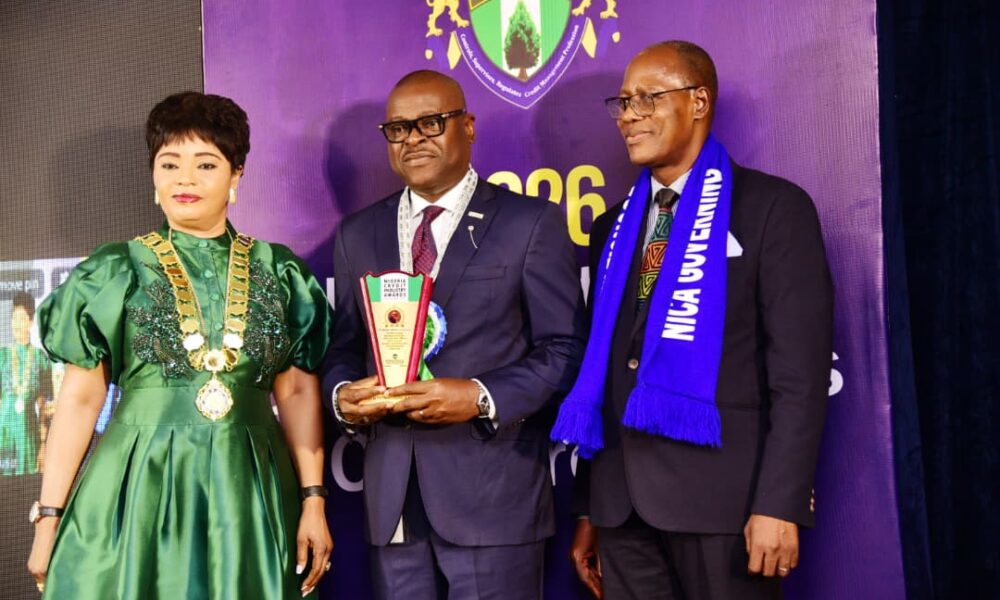
Among the recipients was Dr. Adeyeri Abayomi Folaranmi, FICA, Managing Director of Flobal Financial Services Limited, who received the award for Most Astute Managing Director/Chief Executive Officer of the Year in Business Innovation and Transformational Leadership.
Speaking after receiving the award, Adeyeri described the recognition as an encouragement to pursue the company’s transformation agenda, which includes moving beyond the traditional finance house model towards becoming a commercial banking institution by 2028.
He identified the repositioning as one of the most significant decisions he had taken in the past year, explaining that the company’s approach involved building a community of customers, business partners and investors who share its values and long-term vision.
“Our philosophy is simple: those who believe in a business, patronise its services and benefit from its growth should also have an opportunity to participate in building its future,” he said.
Adeyeri also highlighted the importance of technology, stronger capitalisation, strategic partnerships and institutional development in preparing the company for the evolving financial services landscape.
He said his ambition was to build an institution “that will stand the test of time” while creating lasting value for its stakeholders and Nigeria’s financial services sector.
On leadership and execution, he maintained that strategic planning must be supported by measurable targets, clearly assigned responsibilities and regular performance assessments. “Strategy without execution is merely an ambition,” he said.
Another recipient, Dr. Kalu Keinley Nnachi, MICA, Managing Director of Sikora Microfinance Bank, Umuahia, received recognition for Strategic Decision-Making and Business Resilience. He described the award as recognition of the bank’s achievements and an incentive to pursue greater institutional growth.
Nnachi said the recognition reinforced his commitment to strengthening the bank’s operations and improving its capacity to navigate challenges within the financial services industry.
Similarly, Francis Uchenna Nwanze, KSM, FICA, Head of Credit Management at First Generation Mortgage Bank Limited, was named Chief Credit Risk Officer of the Year.
He attributed the recognition to years of professional service and commitment to credit administration, describing the award as particularly significant because it came from the professional institution responsible for advancing standards in the credit management industry.
Delivering a goodwill message on behalf of the Chairman of Channels Media Group, Dr. John Momoh, FICA, Kingsley Datubor Uranta commended NICA for providing a platform for meaningful discussions on the development of Nigeria’s credit industry.
He described the conference theme as timely, noting that sustainable economic growth depended on trust, financial discipline, accountability and responsible financial practices.
Uranta said credit managers played an important role in promoting responsible lending, expanding financial inclusion and strengthening confidence in the economy.
He also described the conference as an opportunity for professional development, knowledge-sharing and constructive engagement among industry stakeholders, while wishing participants fruitful deliberations.
The central message from the Lagos conference was clear: money alone cannot build a prosperous economy. Sustainable economic development also requires responsible borrowers, professionally trained credit managers, efficient judicial institutions, reliable credit information systems and accountable leadership.
Building a creditworthy Nigeria, the speakers agreed, is a shared responsibility that demands a fundamental shift in the country’s financial culture and the commitment of citizens, lenders, regulators, businesses and government alike.